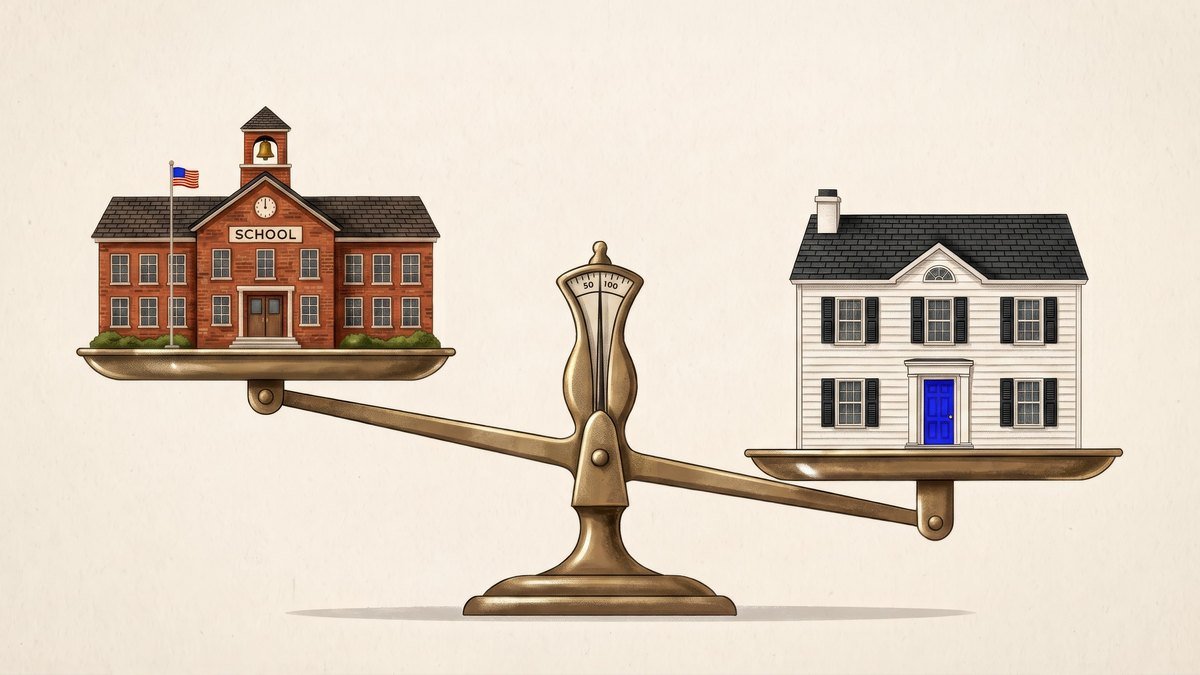
For parents with school-age children, deciding where to buy a home can come with a very expensive question: Do you pay more for a home in a highly rated public school district or buy cheaper somewhere else and invest the price difference in a private school?
At first glance, a private school seems to be the more expensive option. Tuition is money you spend and never see again, while a more expensive home gives you an asset that you can use to build equity and appreciate in value over time.
But the calculation is not that simple. Higher property taxes, a larger down payment, mortgage interest, and the opportunity cost of tying more money into a home also factor in.
So which option actually makes a family better off? We crunched the numbers in the Chicago area over a 13-year period. In our example, buying in the more expensive public school district came out on top (though not for the reason you might think).
A home for $892,250 or a private school for $30,000 a year?
Consider two hypothetical families with a child entering kindergarten.
One buys a home for about $892,250 in Wilmette, Illinois, where families have access to well-regarded public schools, including New Trier Township High School.
The other buys a house in Chicago for about $383,000 and sends his child to the Chicago Waldorf School, where tuition currently ranges from about $28,000 to $35,000 per year, depending on the class.
Both families pay property taxes. This is important.
“This scenario makes families compare a mortgage payment to a college tuition bill. That’s a limited comparison because in both cases you pay school taxes,” he says Colton PaceCo-founder and CEO of Ownwell.
To see how the two options might play out, we modeled 13 years, assuming a 20% down payment, a 30-year mortgage at 6.66%, a 3% annual increase in home value, a 3% annual growth in property taxes and private school tuition, and a 5% return that the Chicago family could invest instead of putting into the more expensive home.
Families can stand here when their child graduates:
| Wilmette and public school | Chicago and private school | |
|---|---|---|
| Starting price for the house | $892,250 | $383,000 |
| down payment | $178,450 | $76,675 |
| Estimated property taxes over 13 years | $251,000 | $84,000 |
| Estimated K-12 Tuition Costs | $0 | $501,000 |
| Estimated home equity after 13 years | $751,000 | $323,000 |
| Estimated savings invested | — | $311,000 |
| Estimated net worth after 13 years | $751,000 | $634,000 |
After 13 years, the Wilmette family has home equity of approximately $751,000. The Chicago family has about $323,000 in home equity and an estimated $311,000 invested elsewhere, for a total net worth of about $634,000. In our model, that equates to a benefit of about $117,000 for the Wilmette family.
Of course, if the rate of home appreciation, investment returns, tuition increases, property taxes, or the specific homes and schools involved change, the gap can shrink, grow, or even reverse. But the exercise shows why comparing a mortgage payment to a college tuition bill doesn’t tell the whole story.
Add a second child and the math changes quickly
Our example becomes much more lopsided when another child comes into play.
“The tax on your property will be about the same whether you have one or five children. However, the amount you pay to send your children to private school will increase dramatically with each new child,” he says Melanie Zimmermana real estate agent at MVP Executive Development.
Chicago Waldorf’s current tuition ranges from $28,200 for kindergarten to $35,300 for high school. At today’s prices, a 13-year term would be about $414,000. Assuming tuition increases by 3% annually, a child’s K-12 cost in our model is approximately $501,000.
If two children attend the same school, a family could easily be looking at around $1 million in combined tuition depending on their ages, tuition increases, financial aid and any sibling discounts.
Meanwhile, the Wilmette family’s mortgage and property taxes don’t double because they have another child.
That’s one reason Zimmerman says the scales could tip toward the more expensive public school district once a family has two or three children.
Taxes could soften the blow, but don’t count on today’s rules forever
Tax relief must be taken into account on both sides.
For 2026, taxpayers who itemize can deduct up to $40,400 in state and local taxes, with this deduction gradually tapering off for higher-income households. That could make the burden of high property taxes a little less painful for some families.
Private school families also have potential tax breaks. Beginning in 2026, up to $20,000 per beneficiary per year can be withdrawn tax-free from a 529 plan for qualified K-12 expenses.
But families making a 13-year decision shouldn’t assume that today’s tax rules will apply to their child’s entire education.
“If you do a 15-year model, you can’t apply today’s rules to all 15 years,” Pace says. “There are too many political factors at play.”
The cheaper home may offer you something else: flexibility
There’s one big advantage of the cheaper home/private school route that isn’t clearly reflected in a net worth calculation: you have more options to change course.
If a parent loses their job or takes time away from work, or the family’s finances change for other reasons, private school tuition may be able to be reduced through financial aid or eliminated by transferring to a public school. A larger mortgage and property tax burden is much harder to get rid of without selling the home.
“Higher fixed housing costs limit a household’s ability to create short-term flexibility in its cash flow,” says Zimmerman.
This is not necessarily an argument against buying in a more expensive area. But Zimmerman says families should make sure the higher housing payment doesn’t put a dent in their budget before counting on future appreciation to make the decision worth it.
Remember that your children will eventually graduate
It’s worth asking one final question before paying a premium for a particular school district: Would you still want to live there if the schools weren’t part of the equation?
“I remind our clients who are weighing these options that buying an expensive home often takes longer than the kids are in school,” he says Jeremy OlsherDirector at Mizner Residential Group – Compass FL. “So when their children graduate, they have to ask themselves, will they still be happy with the home and its location, and will that location maximize the return on investment when it comes time to downsize or retire?”
Ultimately, neither option is automatically cheaper. For one child, our example in the Chicago area was about $117,000 ahead after 13 years in the more expensive private schools and public schools. With multiple children, the bill could trend even further in that direction, as college fees multiply while housing costs largely do not.
But the better choice is one that your family can comfortably afford today and that still makes sense even if your income, family size, or plans look very different 13 years from now.